Gtbank’s H1 2026 Disaster: Delayed Confession Of A Bank In Decline
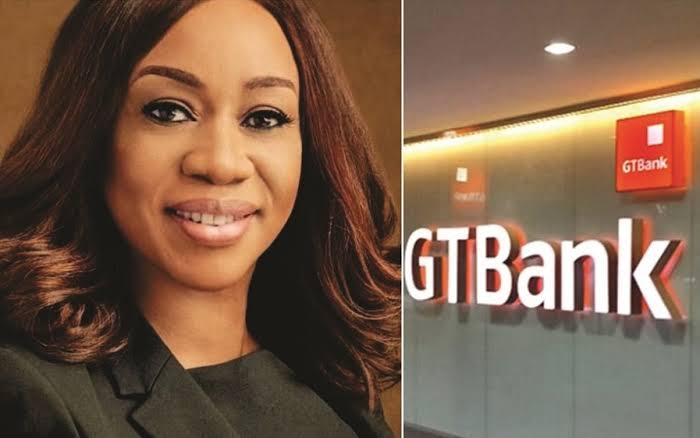
The figures have finally been released, and they are as disastrous as expected given the delays. After weeks of hiding behind regulatory approvals while its competitors released their half-year figures to the market, Guaranty Trust Holding Company Plc has revealed a set of results that can only be described as a planned disaster and a portrait of institutional decay disguised as stability.
For the six months ending June 30, 2026, GTCO reported a profit after tax of ₦414.19 billion, a humiliating 7.76% drop from the ₦449.01 billion recorded in the same period of 2025. In an economy where banking sector assets are expanding, deposits are increasing, and credit channels are reopening, GTBank somehow managed to orchestrate a contraction in profits.
Let that sink in. While the Nigerian economy is growing, monetary policy is stable, and customer deposits across all sectors soar, GTBank’s net profits declined. The bank that once stood for excellence in Nigerian banking now seems to represent mediocrity, and it does so with the confidence of an institution that has forgotten what excellence means.
The headline figures were quite shocking, but the underlying damage is far worse. Profit before tax rose a modest 0.35% to ₦603.03 billion, a statistically stagnant figure that required a 65.94% decrease in loan impairment charges to reach. Excluding that extraordinary accounting gain, the underlying business was in freefall. Net fee income, a key indicator of banking health, plummeted 8.98%. Other income fell from ₦70.92 billion to ₦44.35 billion. Operating expenses increased by 7.31%, with depreciation and amortization soaring by 41.82%.
And then there is the tax bomb. Income tax expenditures rose by 24.33% to ₦188.85 billion, virtually eliminating the pre-tax margin. The government collected more because GTBank’s tax planning became as ineffective as its revenue generation. This wasn’t a bank pressured by macroeconomic instability, but a bank defeated by its own incompetence.
The most disappointing aspect was the stagnant balance sheet. Customer loans grew by a mere 0.48%, rising from ₦3.13 trillion to ₦3.15 trillion. Amid a recapitalized economy with a desperate need for credit, GTBank hoarded deposits and invested them in securities instead of lending them to real businesses. Total equity decreased by 2.82%. Retained earnings fell by 5.98%. The bank shrank even further in real terms while projecting an image of stability.
This is the anatomy of failure.
The most devastating indictment of GTBank’s decline comes not from its own historical performance, but from the trajectory of its competitors, especially those led by women who have demonstrated what competent leadership truly means.
At Zenith Bank, Dame Adaora Umeoji recorded a profit after tax of ₦314.02 billion in the first quarter of 2026, representing a moderate increase of approximately 1% year-on-year that dwarfs that of GTBank. This growth occurred in a challenging environment. It was a leadership that found opportunities where others looked for excuses. While GTBank, under the leadership of Miriam Olusanya, saw its profit after tax decrease by almost 8%, Zenith, under Umeoji’s leadership, actually increased its revenue and strengthened its position as Nigeria’s leading financial institution.
This comparison is not only numerical but also philosophical. Umeoji assumed leadership of Zenith Bank and immediately focused on innovation, digital transformation, and rigorous risk management. In contrast, Olusanya heads a bank whose net interest income grew by a mere 2.75%, its fee income declined, and its loan portfolio virtually stagnated. One leader is building while the other remains impassive as the current pulls her under.
Even mid-sized competitors outperformed GTBank. Fidelity Bank, under the leadership of Nneka Onyeali -Ikpe, recorded a 38% growth in gross earnings, reaching ₦434.95 billion in the first quarter of 2026. While Fidelity’s after-tax profit was pressured during the quarter, its earnings dynamism and aggressive balance sheet expansion demonstrate ambition and strategic positioning. These are qualities completely absent from GTBank’s first-half 2026 report.
Let’s be frank about who is responsible. Miriam Olusanya is the CEO of GTBank, the flagship banking subsidiary that generates the majority of GTCO’s revenue and profit. Deposits kept pouring in, up 11.32% to ₦13.97 trillion, because customers still trust the brand. But what has Olusanya done with that trust? She kept the money invested in securities instead of lending it out. She watched as fee income plummeted. She presided over a 17.73% drop in earnings per share, from ₦13.59 to ₦11.18, which directly impoverished shareholders.
Olusanya has been in the position long enough that she can’t blame anyone else for any problems she might have inherited. A collapse in the first quarter of 2025, a drop throughout 2025, another in the first quarter of 2026, and now a disaster in the first half of 2026. This is her track record. A record of declining profitability, dwindling earnings, and strategic paralysis disguised in quarterly press releases as “sustainable earnings” and “core income focus.”
The market is not fooled. While the share price has risen 51% since the beginning of the year, this was simply due to market momentum and the search for dividends, not a show of confidence in the leadership. When it’s all over, and it always is, investors will remember that Olusanya created a bank with dwindling capital, stagnant loans, and an unstable profit engine.
The board of directors has proposed an interim dividend of N1.00 per share. How generous! How predictable! When a bank can’t expand its business, it bribes its shareholders with their own money. The dividend isn’t a reward for good performance but a bribe, a distraction from the fact that earnings per share have plummeted by almost 18%. Shareholders are being paid to look the other way while the bank’s business deteriorates.
The conclusion from the results for the first half of 2026 is a damning verdict. GTBank is no longer a thriving institution. Despite a growing economy with rising deposits, increasing demand for credit, and stable monetary conditions, the bank is generating lower profits, weaker returns, and reduced equity than last year.
Compare this to Access Holding’s books for example, with pre-tax profit in Q1 reaching ₦272.21 billion from N222.78 billion recorded in Q1 2025 (up 22.19% year-on-year) while delivering genuine earnings growth and expanding its loan book. Olusanya’s GTBank, by contrast, is paying out cash it can barely afford to distribute from a balance sheet that is getting weaker by the quarter.
Miriam Olusanya should look at the banking sector as a whole and take note of the achievements, especially of fellow female leadership in other banks. Adaora Umeoji contributed to Zenith’s excellent performance. Nneka Onyeali -Ikpe helped Fidelity significantly increase its core revenue. These women don’t excuse themselves with “normalizing the environment” or “core earnings transitions.” They are simply building, lending, and generating profits.
Meanwhile, Olusanya is managing a decline and the market knows. On September 29, 2019 when the results were published, the stock fell about 3.3% to ₦132.50. The delay in publishing these results was not just a regulatory formality, but a sign of things to come. When a bank takes weeks to publish even an interim report, it’s because the situation is dire and those preparing it are struggling to find a plausible narrative. The narrative is now clear: GTBank, under Olusanya’s leadership, is a bank in decline.